Updated November 2026. Reviewed by Richard W. Taylor.
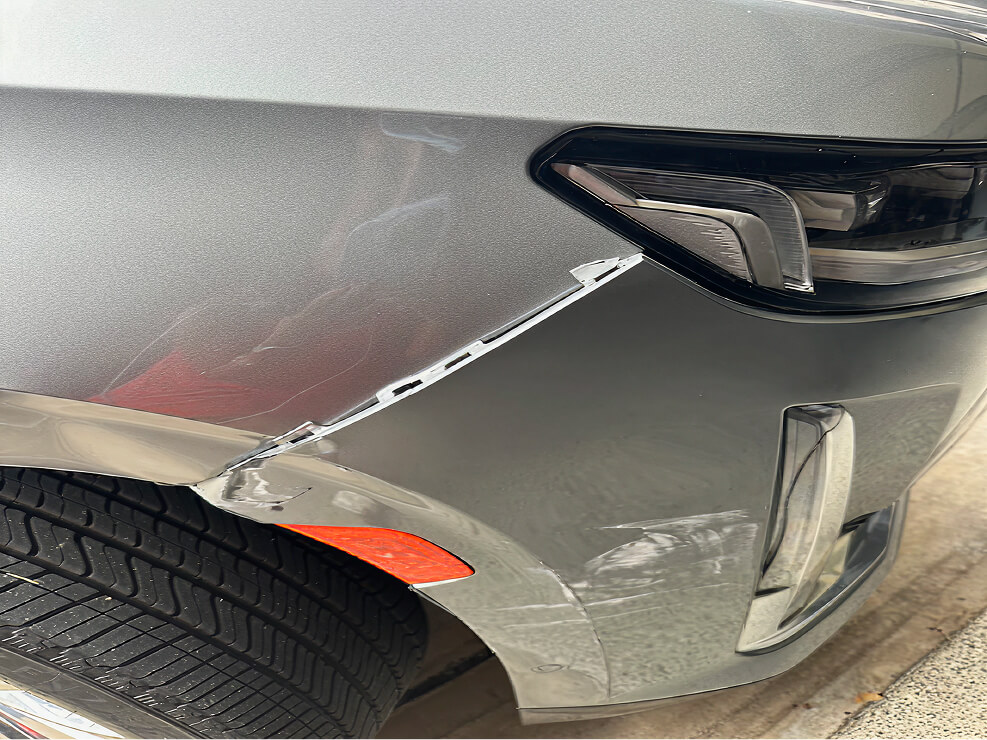
You can file a diminished value claim in Texas against the at-fault driver’s insurance company. Diminished value is the resale value your car loses because it now has an accident history, even after quality repairs. Texas allows that claim against the other driver, and in some cases through your own uninsured or underinsured motorist coverage, but not under your own collision coverage. Here is how a diminished value claim in Texas works, the deadlines that apply, and how to file one.
Key takeaways
- Texas allows a diminished value claim against the at-fault driver’s insurance company, in a third-party claim.
- Your own insurer does not owe diminished value under your collision coverage, according to the Texas Supreme Court.
- Your own uninsured or underinsured motorist coverage may pay for lost market value, according to the Texas Department of Insurance.
- You generally have 2 years from the accident to file a property damage lawsuit in Texas.
- If the insurer will not pay, Texas justice court, often called small claims court, hears claims up to $20,000.
Can you file a diminished value claim in Texas?
Yes, against the at-fault driver’s insurer. The Texas Department of Insurance has said that an insurer may be obligated to pay a third-party claimant for any loss of market value of the claimant’s car, regardless of the completeness of the repair. The same bulletin says an insurer may owe a first-party claimant for lost market value under the uninsured/underinsured motorist coverage of the policy.
A claim under your own collision coverage is different. In 2003, the Texas Supreme Court held in American Manufacturers Mutual Insurance Co. v. Schaefer that an auto policy does not require the insurer to pay its own policyholder for diminished value once the car is repaired.
Texas diminished value claims at a glance
| Item | Texas |
|---|---|
| Claim against the at-fault driver’s insurer | Yes, third-party claim |
| Claim under your own collision coverage | No (Schaefer, 2003) |
| Claim through uninsured or underinsured motorist coverage | May be owed, per TDI Bulletin B-0027-00 |
| Deadline to sue | 2 years for property damage |
| Justice court limit | $20,000 |
| Appraisal clause in your own policy | Required in policies issued or renewed from January 1, 2026 |
How to file a diminished value claim in Texas
- Finish the repairs. A diminished value claim is based on the final repair bill, so wait until the work is done and keep the full invoice.
- Confirm who was at fault. A third-party claim goes to the at-fault driver’s insurer, so get the claim number and the adjuster’s contact details.
- Get an independent appraisal. A documented appraisal shows how much value your car lost, based on the repair bill, the actual damage and current retail market data for comparable cars with a clean history.
- Send a written demand. Send the appraisal with a demand letter to the at-fault driver’s insurer and keep a copy of everything.
- Track the 2-year deadline. If the claim does not settle, you can file in justice court for claims up to $20,000, as long as you act within the limitations period.
DVAC provides the appraisal report, the demand letter, claim strategy and guidance through resolution. You communicate with the insurance company directly, and we advise you on what to say and how to respond.
What if the Texas insurer says no?
Insurers often start with a low offer or deny diminished value outright. Ask the adjuster to explain the denial in writing and to respond to the specific figures in your appraisal. If the claim still does not settle, Texas justice court handles claims up to $20,000, excluding interest and court costs, according to Texas Law Help. A justice court can award money, so a documented appraisal is the core of your case. For larger claims or legal questions, talk to a Texas attorney.
Texas appraisal clause law (Senate Bill 458)
Texas Senate Bill 458 requires personal auto and residential property policies delivered, issued or renewed in Texas from January 1, 2026 to include an appraisal provision for disputes over the amount of loss. The appraisal award binds both sides, except for fraud, accident or material mistake, according to the enrolled bill analysis. This applies to your own policy, such as a total loss or an uninsured motorist claim. If the appraisal clause is invoked, DVAC negotiates and resolves the value with the third-party appraiser the insurance company hires. For totaled cars, see our Texas total loss guide and the Texas total loss threshold.
Texas diminished value case studies
See how Texas owners documented their loss: a 2024 Ford Bronco and a Cadillac claim.
Texas diminished value questions
Is Texas a diminished value state?
Yes, for third-party claims against the at-fault driver’s insurer. Your own collision coverage does not owe diminished value under the 2003 Schaefer decision.
How long do I have to file a diminished value claim in Texas?
Texas generally allows 2 years from the accident to file a property damage lawsuit, so start the claim well before that deadline.
Can I take a diminished value claim to small claims court in Texas?
Yes. Texas justice court hears claims up to $20,000, excluding interest and court costs.
Can I claim diminished value through my uninsured motorist coverage in Texas?
Possibly. The Texas Department of Insurance has said an insurer may owe lost market value under uninsured or underinsured motorist coverage. Check your policy and ask your insurer in writing.
Sources
- Texas Department of Insurance, Commissioner’s Bulletin B-0027-00 (April 6, 2000).
- American Manufacturers Mutual Insurance Co. v. Schaefer, 124 S.W.3d 154 (Tex. 2003), as reported by Insurance Journal.
- Texas Civil Practice and Remedies Code 16.003, two-year limitations period (Texas Law Help summary).
- Texas Law Help, How to Sue in Justice Court (Small Claims Court).
- Texas Senate Bill 458 (89th Legislature), enrolled bill analysis.
This page is general information, not legal advice. Diminished value rules can change and depend on the facts of your claim, so confirm current requirements with your state insurance department or an attorney.