
Updated November 2026. Reviewed by Richard W. Taylor.
You can file a diminished value claim in Florida against the at-fault driver’s insurance company. Diminished value is the resale value your car loses because it now has an accident history, even after the repairs are done well. Florida courts do not require your own insurer to pay it under a standard repair-or-replace policy, so a Florida diminished value claim is a third-party claim. Here is how it works, the deadline that changed in 2023, and how to file.
Key takeaways
- Florida diminished value claims go against the at-fault driver’s insurance company.
- Your own insurer does not owe diminished value under a standard repair-or-replace policy, according to the Florida Supreme Court’s 2002 Siegle decision.
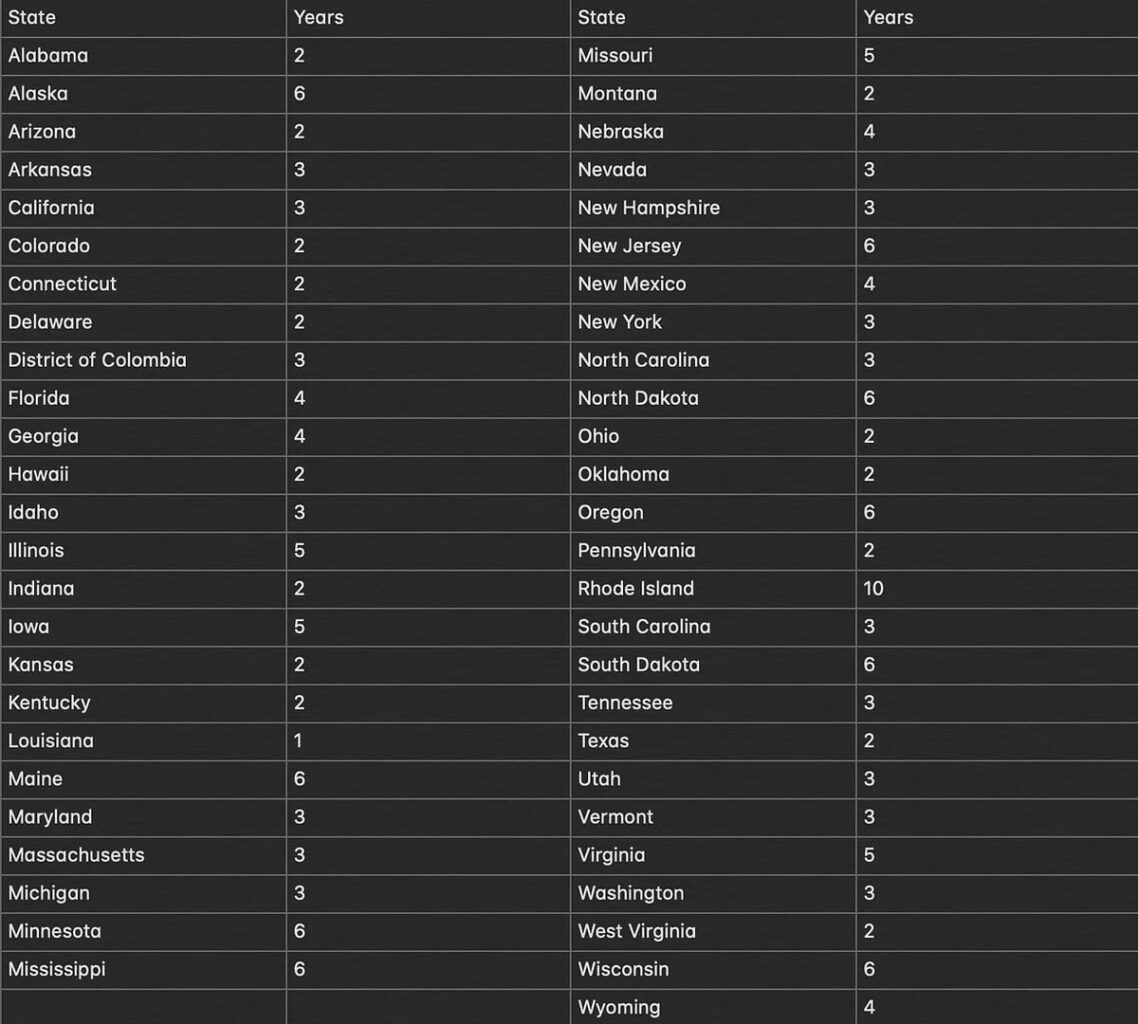
- Florida’s deadline for negligence claims is 2 years, shortened from 4 years in 2023, so act early.
- Florida small claims court hears claims up to $8,000, not counting costs, interest and attorney fees.
- A documented appraisal, built from your repair bill and current market data, is the core of a Florida diminished value claim.
Can you file a diminished value claim in Florida?
Yes, against the driver who caused the accident. Florida courts have long treated lost market value as part of the property damage an at-fault driver may owe; the leading appellate case is McHale v. Farm Bureau Mutual Insurance Co. (1982).
A claim against your own insurer is different. In Siegle v. Progressive (2002), the Florida Supreme Court held that once the insurer repaired the car under the policy’s repair-or-replace terms, the policy did not require it to also pay for diminished value. So check your own policy before relying on it, and plan to file against the at-fault driver’s insurer.
Florida diminished value claims at a glance
| Item | Florida |
|---|---|
| Claim against the at-fault driver’s insurer | Yes, third-party claim |
| Claim under your own policy | Generally no (Siegle, 2002) |
| Deadline for negligence claims | 2 years, Fla. Stat. 95.11(5)(a) |
| Small claims limit | $8,000 |
| Key cases | McHale (1982), Siegle (2002) |
How long do you have to file in Florida?
Florida shortened its deadline for lawsuits founded on negligence from 4 years to 2 years in 2023, for claims arising after the change took effect. A car accident claim against an at-fault driver is usually a negligence claim, so treat 2 years from the accident as your deadline under Fla. Stat. 95.11(5)(a). Older guides, including some still online, list 4 years. If your accident is close to either date, confirm the deadline with a Florida attorney.
How to file a diminished value claim in Florida
- Finish the repairs and keep the final repair bill, since the claim is based on it.
- Get the at-fault driver’s claim details: the insurer, the claim number and the adjuster.
- Get an independent appraisal. A documented appraisal shows how much value your car lost, based on the repair bill, the actual damage and current retail market data for comparable cars with a clean history.
- Send a written demand with the appraisal to the at-fault driver’s insurer, and keep copies.
- Watch the 2-year deadline. If the claim does not settle, Florida small claims court hears claims up to $8,000.
DVAC provides the appraisal report, the demand letter, claim strategy and guidance through resolution. You communicate with the insurance company directly, and we advise you on what to say and how to respond.
What if the Florida insurer refuses to pay?
Ask the adjuster to put the denial in writing and to respond to the figures in your appraisal. If the claim still does not settle, Florida small claims court handles claims up to $8,000, not counting costs, interest and attorney fees, under Small Claims Rule 7.010. For larger claims or legal questions, talk to a Florida attorney. If your car was totaled instead of repaired, see our Florida total loss guide and the Florida total loss threshold.
Florida diminished value case studies
See how Florida owners documented their loss: a 2022 Cadillac Escalade and a Chevrolet Silverado claim. For a longer walkthrough of Florida’s rules, read diminished value in Florida.
Florida diminished value questions
Is Florida a diminished value state?
Yes, for third-party claims against the at-fault driver’s insurer. Your own insurer generally does not owe diminished value after a full repair, under Siegle (2002).
How long do I have to file a diminished value claim in Florida?
Plan on 2 years from the accident, Florida’s deadline for negligence claims since 2023.
What is the small claims limit in Florida?
$8,000, not counting costs, interest and attorney fees.
Do I need a lawyer for a Florida diminished value claim?
Not always. Many owners send a demand with an independent appraisal on their own, but talk to a Florida attorney for larger claims or legal questions.
Sources
- Siegle v. Progressive Consumers Insurance Co., 819 So. 2d 732 (Fla. 2002) (Justia).
- McHale v. Farm Bureau Mutual Insurance Co., 409 So. 2d 238 (Fla. 3d DCA 1982).
- Fla. Stat. 95.11, limitations other than for the recovery of real property (Florida Legislature).
- The Florida Bar, amendment to Small Claims Rule 7.010 ($8,000 limit).
This page is general information, not legal advice. Diminished value rules can change and depend on the facts of your claim, so confirm current requirements with your state insurance department or an attorney.