Total Loss in Hawaii: How Cars Are Totaled and What Your Car Is Worth
Hawaii does not use a fixed percentage. For title purposes, a car is a total loss when it has material damage to key systems and the projected repair cost exceeds its market value. Hawaii also has detailed rules on how insurers settle a total loss, including paying the general excise tax and ownership fee on a replacement. Here is how it works and what to do if the offer looks low.
Quick note: this is about total loss, when the car is not being repaired. If your car was repaired but is now worth less, that is diminished value, a different process.
Start The Total Loss Appraisal Process
If your insurer’s offer does not look right, do not rely on guesswork. DVAC can review the valuation, identify problems, and provide an independent total loss appraisal to help you challenge a low settlement offer.
No obligation required.
A+ Rating on BBB | Servicing Clients Nationwide
Home » Total Loss Appraisal » Total Loss Appraisal in Hawaii
Key takeaways
- Hawaii has no fixed percentage: for title purposes, a car is a total loss only if it has material damage to its electronics, frame, unitized structure or suspension and the projected repair cost exceeds its market value.
- An insurer settling a total loss must either provide a replacement car or pay cash based on the car’s retail value from sources that reflect its market value.
- If you buy a replacement within 30 days of receiving a cash settlement, the insurer reimburses the general excise tax and certificate of ownership fee, as long as you send proof within 33 days.
- If you cannot find a comparable car for the insurer’s value within 30 days, the insurer must take further steps, such as paying the difference or using the appraisal provision.
- If the offer looks low, an independent total loss appraisal gives you a documented Hawaii market value to challenge it.
What is Hawaii’s total loss threshold?
Hawaii does not set a percentage. Its motor vehicle law says that a vehicle is a total loss only if there is material damage, including flood damage, to its electronics, frame, unitized structure or suspension system, and the projected cost of repair exceeds the vehicle’s market value at the time of the incident. In practice, that is a 100% standard. (Source: HRS 286-2. General information, not legal advice; confirm the current rule for your situation.)
Hawaii total loss at a glance
Item | Hawaii |
Threshold | Repairs exceed market value, with material damage |
Rule type | 100% standard |
Settlement methods | Replacement car or cash |
Cash value based on | Retail value from sources reflecting market value |
Excise tax and ownership fee | Reimbursed if you buy within 30 days |
Proof of purchase | Within 33 days of the settlement |
Dealer prep charges | Not allowed as deductions |
What you are paid | Retail value plus tax and fee, less your deductible |
How they decide if your car is totaled in Hawaii
The insurer estimates the cost to repair your car and compares it to the car’s market value at the time of the incident. Under Hawaii’s title law, the car is a total loss when the projected repair cost exceeds that value and the damage reaches the electronics, frame, unitized structure or suspension. For example, a car worth $20,000 with structural damage is a total loss once the repair estimate goes above $20,000.
Because the whole decision rests on your car’s value, getting that number right matters. It is worth understanding actual cash value versus fair market value.
How Hawaii requires your payout to be calculated
Under HRS 431:10C-309, the insurer must follow either a replacement method or a cash settlement method. For a cash settlement, HRS 431:10C-311 says:
- The value is based on the car’s retail value from sources that reflect its market value.
- Dealer quotes, for cars actually on the dealer’s lot, and newspaper ads can be used, but not as the only sources, and the identification number of any quoted car must be in the claim file.
- If your car is not listed in the insurer’s usual source, estimates from at least three licensed dealers may be used, accounting for its condition before the loss.
- Charges such as “get ready to go” or dealer preparation may not be deducted.
If you cannot find a comparable car in Hawaii
If, within 30 days of receiving the cash settlement, you cannot buy a comparable car of like kind and quality for the insurer’s market value, and you have found one priced higher, the insurer must act. It can locate a comparable car for you at its value through a licensed dealer, pay the difference or complete the purchase, or settle the value through your policy’s appraisal provision. The insurer must tell you in writing at settlement that it will reopen the claim if these conditions are met.
Does a Hawaii total loss payout include excise tax and fees?
Yes, with a deadline. Under HRS 431:10C-312, if you buy a replacement car within 30 days of receiving a cash settlement, the insurer reimburses the general excise tax and certificate of ownership fee, up to the amount payable on your totaled car’s value. You must send proof of the purchase and the tax within 33 days of the settlement. The insurer may instead pay these amounts to you at settlement, and it must explain the procedure in writing. If the other driver’s insurer pays your claim, Hawaii law also requires it to pay the tax and ownership fee, subject to its policy limit.
How your total loss payout is set
Your payout should equal what it would cost to buy the same car again today in your local Hawaii market, which can differ a lot from mainland prices. Insurers often use a third-party valuation report, such as a CCC valuation, that compares similar vehicles, then adjusts for your car’s details. Check that the comparison cars are from your island. Here is what moves the number, and for a closer look, see what your totaled car is worth:
What affects your payout | How it moves the number |
Mileage | Lower miles raise value; a wrong higher reading lowers it |
Condition | Clean condition raises value; heavy deductions lower it |
Trim and options | Factory options and higher trims add value, if counted |
Local market | Prices for the same car in Hawaii set the baseline |
Comparison cars | The vehicles used for comparison can pull the number up or down |
Can you keep your totaled car in Hawaii?
Often, yes, if your insurer agrees. The insurer deducts the salvage value from your payout. A repaired total loss car is treated as a rebuilt vehicle under Hawaii’s title law, so check the county’s rebuilt vehicle inspection and title steps before you decide, and ask for the salvage deduction in writing.
What to do if your Hawaii total loss offer looks low
Ask which sources the insurer used and whether they reflect the market in Hawaii. Check that no dealer prep charges were deducted, and compare the report to current listings for the same year, make and model on your island. If you cannot find a comparable car for the amount offered, use the 30-day reopening right, and keep your receipts so the excise tax and ownership fee are reimbursed.
Then check your policy for an appraisal clause, which Hawaii’s law names as one way to settle the value, and see how to dispute a total loss settlement offer step by step.
How an independent appraisal helps in Hawaii
Hawaii requires values from sources that reflect your car’s market value, and a documented appraisal shows what that market really is. Our total loss appraisal service values your vehicle using comparable vehicles in your local market and gives you the documentation to challenge a low offer. You stay in contact with your insurance company, and we advise you on what to say and what to do next. If the appraisal clause is invoked, DVAC negotiates and resolves the value with the third-party appraiser the insurance company hires.
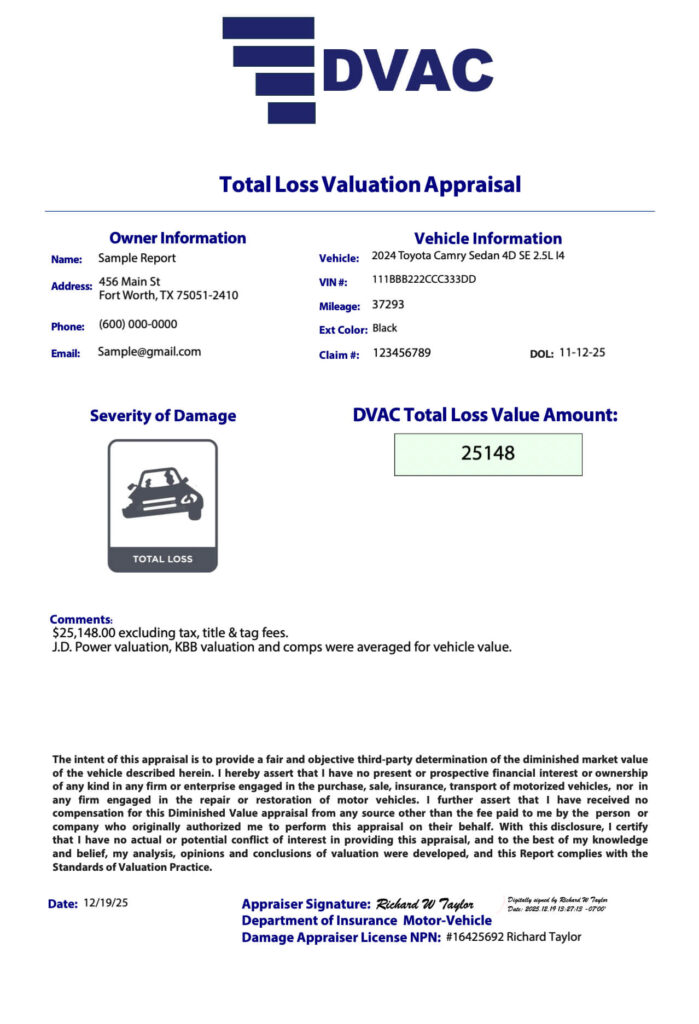
Look at a sample total loss appraisal report to see what the insurer receives.
Hawaii total loss questions
Does Hawaii have a total loss percentage?
No. For title purposes, a car is a total loss only with material damage to key systems and a projected repair cost above its market value.
Does my Hawaii insurer pay excise tax on a replacement car?
Yes, if you buy within 30 days of a cash settlement and send proof within 33 days. The insurer may also pay it at settlement.
What if I cannot find a comparable car for my Hawaii settlement?
Within 30 days, the insurer must find one for you at its value, pay the difference, or use the appraisal provision.
What does an insurer pay for a totaled car in Hawaii?
The car’s retail value plus the excise tax and ownership fee, less your deductible if you claim on your own policy, and less the salvage value if you keep the car. Learn more in total loss settlements: what you need to know.
Get a free Hawaii total loss appraisal consultation
If your Hawaii offer feels low, start your appraisal or call (877) 879-0101 for a free consultation, and we will give you a documented market value to support your claim.
Real Reviews, Real Results
Total Loss Appraisal Report:
Wondering what’s in a DVAC appraisal? Take a look at this recent appraisal we completed for a client.