Total Loss in Indiana: The 70% Rule Explained, and What Your Car Is Worth
Indiana’s 70% total loss rule is often quoted, but for a car covered by an insurance policy, the decision belongs to your insurer: a car becomes salvage when the insurer decides it is economically impractical to repair and settles the claim. Indiana also requires insurers to pay sales tax on top of your car’s value. Here is how the rule really works, how your payout is set, and what to do if the offer looks low.
Quick note: this is about total loss, when the car is not being repaired. If your car was repaired but is now worth less, that is diminished value, a different process.
Start The Total Loss Appraisal Process
If your insurer’s offer does not look right, do not rely on guesswork. DVAC can review the valuation, identify problems, and provide an independent total loss appraisal to help you challenge a low settlement offer.
No obligation required.
A+ Rating on BBB | Servicing Clients Nationwide
Home » Total Loss Appraisal » Total Loss Appraisal in Indiana
Key takeaways
- For an insured car, Indiana sets no fixed percentage. The car needs a salvage title when the insurer decides it is economically impractical to repair and settles the claim.
- The 70% figure applies to self-insured businesses and to people who buy a car after it was damaged, not to a typical insured driver.
- Indiana’s salvage title rule covers vehicles made within the last 7 model years.
- Indiana requires insurers to pay sales tax on top of your car’s value, at the time they pay you.
- If the offer looks low, an independent total loss appraisal gives you a documented Indiana market value to challenge it.
What is Indiana’s total loss threshold?
Under Indiana law, a vehicle made within the last 7 model years needs a salvage title in any of these cases:
- An insurance company has determined that it is economically impractical to repair the vehicle and has made an agreed settlement with the insured or claimant.
- The owner is a business that insures its own vehicles, or bought the vehicle after it was damaged, and the cost of repairing it exceeds 70% of its fair market value immediately before the damage.
- The vehicle is flood damaged.
So for most drivers with an insurance policy, the 70% test is not what decides the claim. The insurer’s judgment does, which makes your car’s value even more important. (Source: IC 9-22-3-3. General information, not legal advice; confirm the current rule for your situation.)
Indiana total loss at a glance
Item | Indiana |
Insured cars | No fixed percentage; the insurer decides it is economically impractical to repair |
Self-insured or bought after damage | Salvage when repair cost exceeds 70% of fair market value |
Vehicles covered by the salvage rule | Made within the last 7 model years |
Salvage value added? | No |
Sales tax | Paid on top of the car’s value, at settlement |
What you are paid | Fair market value of the car plus sales tax, less deductions |
How they decide if your car is totaled in Indiana
For an insured car, the insurer compares its repair estimate with what your car was worth before the accident and decides whether repairing it is economically practical. There is no set percentage, so two insurers can reach different answers on the same damage. A low value for your car makes a total loss more likely and lowers your payout at the same time.
It is worth understanding actual cash value versus fair market value before you accept any figure.
Does an Indiana total loss payout include sales tax?
Yes. The Indiana Department of Insurance directs insurers to pay sales tax in addition to the amount for the totaled vehicle, at the time they pay you for the loss, not only after you buy a replacement. The sales tax is computed on the amount the insurer pays for your car (Bulletin 82). Check that the tax appears on your settlement and that it is based on the full payout.
How your total loss payout is set
Your payout should equal what it would cost to buy the same car again today in your local Indiana market. Insurers usually set it with a third-party valuation report, such as a CCC valuation, that compares similar local vehicles, then adjusts for your car’s details. Here is what moves the number, and for a closer look, see what your totaled car is worth:
What affects your payout | How it moves the number |
Mileage | Lower miles raise value; a wrong higher reading lowers it |
Condition | Clean condition raises value; heavy deductions lower it |
Trim and options | Factory options and higher trims add value, if counted |
Local market | Prices for the same car in Indiana set the baseline |
Comparison cars | The vehicles used for comparison can pull the number up or down |
Can you keep your totaled car in Indiana?
Often, yes, if your insurer agrees. The insurer deducts the car’s salvage value from your payout, and because the insurer has settled it as a total loss, a car made within the last 7 model years will need a salvage title. Ask for the salvage deduction in writing before you decide.
What to do if your Indiana total loss offer looks low
Read the valuation report line by line and compare it to current listings for the same year, make and model in Indiana. Look for the wrong mileage, missing options, or comparison cars that do not match yours, and check that sales tax is included. If your research lands above the offer, that is a strong reason to ask for a corrected valuation.
Next, check your policy for an appraisal clause, a provision many policies include for resolving a disagreement over value, and see how to dispute a total loss settlement offer step by step. If you believe your claim is not being handled properly, you can file a complaint with the Indiana Department of Insurance. The Department reviews whether insurance laws and policy terms were followed, although it cannot set the value of your claim.
How an independent appraisal helps in Indiana
A documented appraisal is the clearest way to show an Indiana car’s real value. Our total loss appraisal service values your vehicle using comparable vehicles in your local market and gives you the documentation to challenge a low offer. You stay in contact with your insurance company, and we advise you on what to say and what to do next. If the appraisal clause is invoked, DVAC negotiates and resolves the value with the third-party appraiser the insurance company hires.
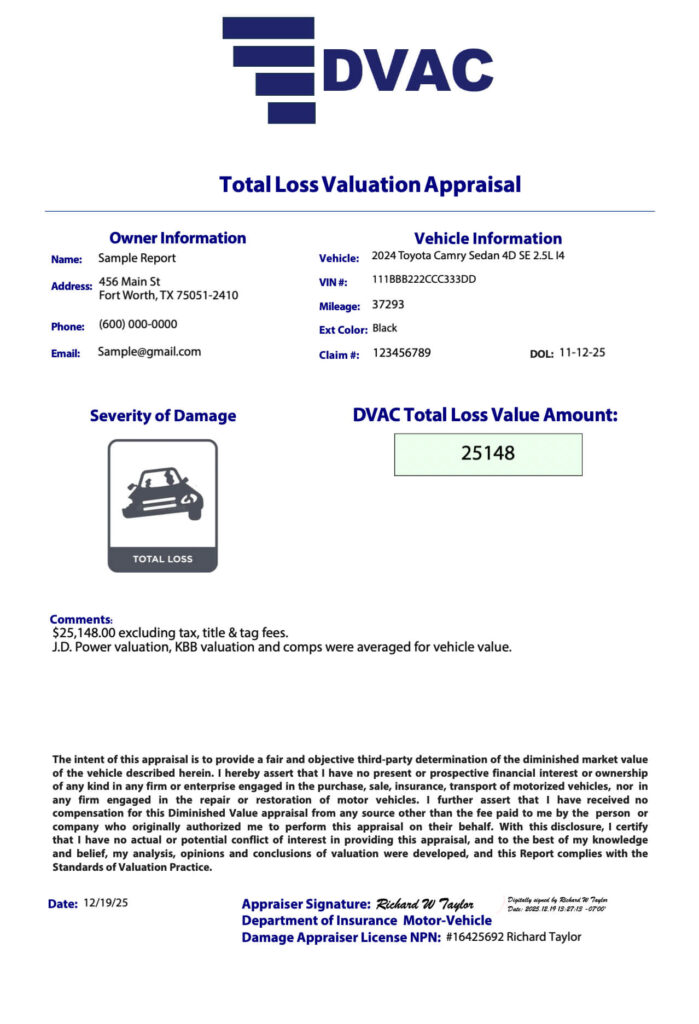
Look at a sample total loss appraisal report to see what the insurer receives.
Indiana total loss questions
Is Indiana a 70% total loss state?
Only in part. The 70% test applies to self-insured businesses and to people who buy a car after it was damaged. For an insured car, the insurer decides whether repair is economically impractical.
Does Indiana’s salvage rule apply to older cars?
The salvage title requirement covers vehicles made within the last 7 model years.
Does my Indiana insurer have to pay sales tax on a totaled car?
Yes. Indiana directs insurers to pay sales tax on top of the car’s value when they pay the claim, computed on the amount paid for the car.
What does an insurer pay for a totaled car in Indiana?
The car’s fair market value plus sales tax, less your deductible if you claim on your own policy, and less the salvage value if you keep the car. Learn more in total loss settlements: what you need to know.
Get a free Indiana total loss appraisal consultation
If your Indiana offer feels low, start your appraisal or call (877) 879-0101 for a free consultation, and we will give you a documented market value to support your claim.
Real Reviews, Real Results
Total Loss Appraisal Report:
Wondering what’s in a DVAC appraisal? Take a look at this recent appraisal we completed for a client.