Total Loss in Kentucky: The 75% Threshold and What Your Car Is Worth
Kentucky uses a 75% threshold: a car needs a salvage title when the cost to repair it exceeds 75% of its retail value in a nationally accepted valuation guide. Kentucky’s insurance rules also set out how your settlement must be calculated, including taxes and fees and a 35-day right to reopen the claim. Here is how it works and what to do if the offer looks low.
Quick note: this is about total loss, when the car is not being repaired. If your car was repaired but is now worth less, that is diminished value, a different process.
Start The Total Loss Appraisal Process
If your insurer’s offer does not look right, do not rely on guesswork. DVAC can review the valuation, identify problems, and provide an independent total loss appraisal to help you challenge a low settlement offer.
No obligation required.
A+ Rating on BBB | Servicing Clients Nationwide
Home » Total Loss Appraisal » Total Loss Appraisal in Kentucky
Key takeaways
- Kentucky uses a 75% threshold: a car needs a salvage title when repairs to its pre-accident condition exceed 75% of its retail value.
- Retail value comes from a nationally accepted used car valuation guide or tool, and the cost of reinstalling a deployed airbag is left out of the 75% test.
- A cash settlement is based on the cost of a comparable car in your local market area, including applicable taxes and fees, less your deductible.
- If you cannot buy a comparable car for the payout, tell your insurer within 35 days of receiving the check and it must reopen the claim.
- If the offer looks low, an independent total loss appraisal gives you a documented Kentucky market value to challenge it.
What is Kentucky’s total loss threshold?
Kentucky’s threshold is 75%. Under state law, a car is a salvage vehicle when the total estimated or actual cost of parts and labor to rebuild it to its pre-accident condition, for legal operation on the road, exceeds 75% of its retail value as set by a nationally accepted used car valuation guide or tool. The cost of reinstalling a deployed airbag system is not counted toward the 75%, though the insurer still includes it in the damage estimate, up to the car’s total retail value. Kentucky updated this section in 2026. (Source: KRS 186A.520, as amended by 2026 HB 144. General information, not legal advice; confirm the current rule for your situation.)
Kentucky total loss at a glance
Item | Kentucky |
Threshold | More than 75% |
Rule type | Percentage threshold |
What counts | Parts and labor to restore pre-accident condition |
Airbags | Reinstallation left out of the 75% test |
Compared with | Retail value in a national valuation guide |
Taxes and fees | Included in a cash settlement |
Reopening the claim | Within 35 days of receiving the check |
What you are paid | Cost of a comparable car plus taxes and fees, less your deductible |
How they decide if your car is totaled in Kentucky
The insurer estimates the cost of parts and labor to return your car to its pre-accident condition and compares it to the car’s retail value in a recognized valuation guide. Parts are priced at current retail cost for parts of like kind and quality, and labor at the rates customary in your community. Once the estimate, not counting airbag reinstallation, exceeds 75% of the value, the car needs a salvage title. For example, if your car’s retail value is $20,000, a repair estimate above $15,000 makes it salvage in Kentucky.
Because the whole decision rests on your car’s value, getting that number right matters. It is worth understanding actual cash value versus fair market value.
How Kentucky requires your payout to be calculated
Kentucky’s settlement standards are in Section 7 of 806 KAR 12:095. On your own policy, the insurer may either:
- Offer a specific comparable replacement car, with all applicable taxes, license fees and other transfer fees paid, at no cost to you other than your deductible; or
- Pay cash based on the actual cost, less your deductible, of a comparable car, including all applicable taxes, license fees that cannot be refunded and other transfer fees.
The cash value must come from a comparable car in your local market area, meaning a reasonable distance around where your car is mainly kept, or from one of at least two quotes from qualified licensed dealers, or from a source that gives consideration to local values. Any deduction, including for salvage, must be measurable, discernable and itemized, and a different method must be documented and fully explained to you.
The 35-day right to reopen your Kentucky claim
If you cannot buy a comparable car for the market value your insurer set, tell the insurer within 35 days of receiving the settlement check. It must then reopen the claim and either pay the difference between its value and the cost of a comparable car you found, or arrange the purchase. Keep copies of the listings and dealer quotes you find, since they are your evidence.
How your total loss payout is set
Your payout should equal what it would cost to buy the same car again today in your local Kentucky market. Insurers usually set it with a third-party valuation report, such as a CCC valuation, that compares similar vehicles, then adjusts for your car’s details. Here is what moves the number, and for a closer look, see what your totaled car is worth:
What affects your payout | How it moves the number |
Mileage | Lower miles raise value; a wrong higher reading lowers it |
Condition | Clean condition raises value; heavy deductions lower it |
Trim and options | Factory options and higher trims add value, if counted |
Local market | Prices for the same car in Kentucky set the baseline |
Comparison cars | The vehicles used for comparison can pull the number up or down |
Can you keep your totaled car in Kentucky?
Often, yes, if your insurer agrees. The insurer deducts the salvage value, which Kentucky requires to be itemized. You then need a salvage title: the owner applies to the county clerk within 15 days of receiving all the necessary paperwork. A car with a salvage title cannot be registered for the road until it is rebuilt and passes inspection. Ask for the salvage deduction in writing before you decide.
What to do if your Kentucky total loss offer looks low
Check the offer against Kentucky’s rule. Are the comparison cars from your local market area? Are taxes and fees included? Is every deduction itemized? Look for the wrong mileage, missing options, or comparison cars that do not match yours, and remember the 35-day reopening right if you cannot find a comparable car for the amount offered.
Then check your policy for an appraisal clause, a provision many policies include for resolving a disagreement over value, and see how to dispute a total loss settlement offer step by step.
How an independent appraisal helps in Kentucky
Kentucky’s rule asks insurers to give consideration to values in your local market, and a documented appraisal shows exactly what those values are. Our total loss appraisal service values your vehicle using comparable vehicles in your local market and gives you the documentation to challenge a low offer. You stay in contact with your insurance company, and we advise you on what to say and what to do next. If the appraisal clause is invoked, DVAC negotiates and resolves the value with the third-party appraiser the insurance company hires.
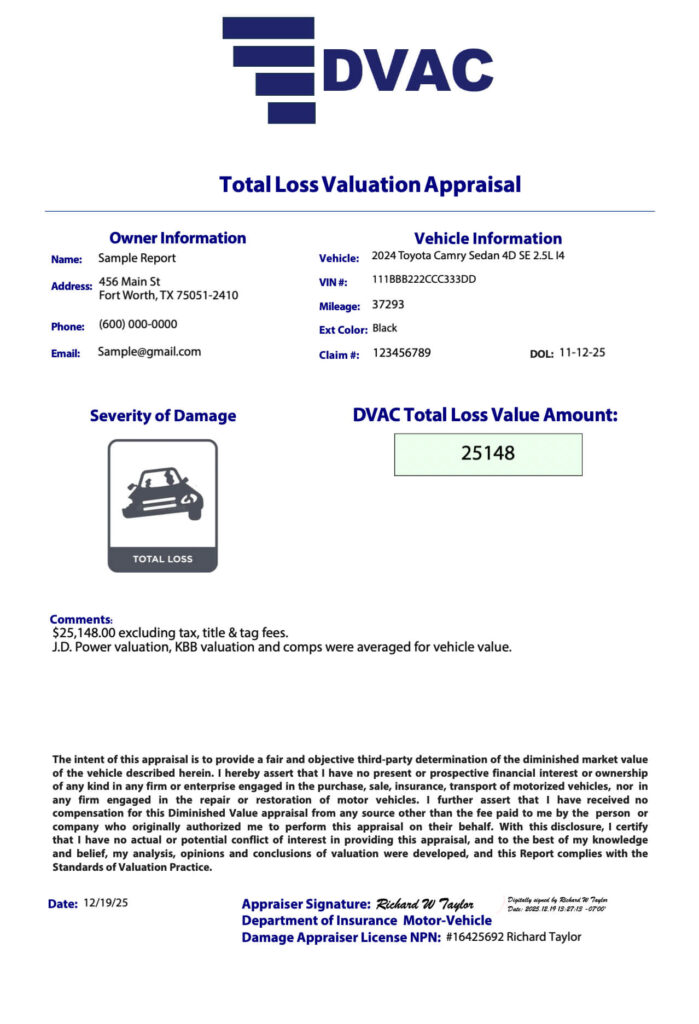
Look at a sample total loss appraisal report to see what the insurer receives.
Kentucky total loss questions
Is Kentucky a 75% total loss state?
Yes. A car needs a salvage title when repairs exceed 75% of its retail value in a national valuation guide.
Do airbags count toward Kentucky’s 75%?
No. The cost of reinstalling a deployed airbag is left out of the 75% test, though the insurer still includes it in the damage estimate.
Does my Kentucky insurer pay sales tax on a totaled car?
Yes. Kentucky’s rule includes applicable taxes, license fees and transfer fees in a cash settlement on your own policy.
What does an insurer pay for a totaled car in Kentucky?
The cost of a comparable car plus taxes and fees, less your deductible if you claim on your own policy, and less the salvage value if you keep the car. Learn more in total loss settlements: what you need to know.
Get a free Kentucky total loss appraisal consultation
If your Kentucky offer feels low, start your appraisal or call (877) 879-0101 for a free consultation, and we will give you a documented market value to support your claim.
Real Reviews, Real Results
Total Loss Appraisal Report:
Wondering what’s in a DVAC appraisal? Take a look at this recent appraisal we completed for a client.